




Optimal Portfolio Selection: Risk Aver ...
Why Optimal Portfolio Selection Starts With the Investor Portfolio theory is sometimes presented... Read More

Investment analysis rarely begins with complete information. An analyst may start with a view about the probability that a company will beat earnings expectations, that a bond issuer will be downgraded, or that an equity factor will continue to work. Then new information arrives: management revises guidance, a rating agency changes its outlook, a macroeconomic release surprises the market, or trading data show unusual order flow.
Bayesian updating provides a disciplined way to revise an existing probability when new evidence becomes available. The point is not to replace judgment with a formula. Rather, the formula forces the analyst to ask the right questions: What did I believe before the new information arrived? How likely is this evidence if the event of interest is true? How likely is the evidence overall? Once those questions are answered, the analyst can convert a prior belief into a posterior belief.
This matters in investment work because markets continuously process incomplete and noisy signals. A single announcement may be informative but also misleading. Bayesian updating helps the analyst avoid two common mistakes: ignoring useful new evidence and overreacting to evidence without considering the base rate or prior probability.
The starting point in Bayesian analysis is the distinction between prior and posterior probabilities.
A prior probability is the probability assigned before considering the new evidence. It may come from historical data, an analyst’s forecast model, sector experience, or a cross-sectional comparison of similar companies.
A posterior probability is the updated probability after the new evidence has been incorporated. It is conditional on the evidence having occurred.
$$ \textbf{Table 1: Bayesian Updating Terminology} \\
\begin{array}{l|c|c}
\textbf{Term} & \textbf{Meaning} & \textbf{Investment Example} \\
\hline
\text{Prior probability} &
{\text{Probability before the new} \\ \text{evidence is considered} }&
{\text{Initial probability that a company} \\ \text{will outperform earnings} \\ \text{expectations}} \\
\hline
\text{Evidence} &
{\text{New information observed by} \\ \text{the analyst} }&
{\text{A company announces a major} \\ \text{customer win before earnings} \\ \text{release}} \\
\hline
\text{Likelihood} &
{\text{Probability of observing the} \\ \text{evidence if a particular event is} \\ \text{true}} &
{\text{Probability of a major customer} \\ \text{win given that earnings will beat} \\ \text{expectations} }\\
\hline
{\text{Marginal probability} \\ \text{of the evidence}} &
{\text{Overall probability of observing} \\ \text{the evidence across all possible} \\ \text{states} }&
{\text{Probability of a major customer} \\ \text{win, regardless of the earnings} \\ \text{outcome} }\\
\hline
\text{Posterior probability} &
{\text{Updated probability after} \\ \text{incorporating the evidence} }&
{\text{Revised probability that the} \\ \text{company will outperform} \\ \text{earnings expectations} }\\
\end{array}
$$
Table 1 shows why Bayesian updating is useful in practice. The analyst is not merely asking whether the evidence looks favorable. The analyst is asking how the evidence affects the probability of the event under analysis. That distinction is central to professional forecasting.
Bayes’ theorem follows from the fact that the joint probability of two events can be written in two equivalent ways. If events \(A\) and \(B\) occur together, then:
$$P(A \mid B)P(B) = P(A \cap B) = P(B \cap A) = P(B \mid A)P(A)$$
Where:
Rearranging gives Bayes’ theorem:
$$P(A \mid B) = \frac{P(B \mid A)P(A)}{P(B)}$$
Where:
The numerator, \(P(B \mid A)P(A)\), captures how much support the new evidence provides for event \(A\). The denominator, \(P(B)\), scales that support by the overall probability of observing the evidence. In exam questions, many errors occur because candidates use the likelihood, \(P(B \mid A)\), as though it were the posterior, \(P(A \mid B)\). These are not the same probability.
Figure 1: Bayesian Updating Process
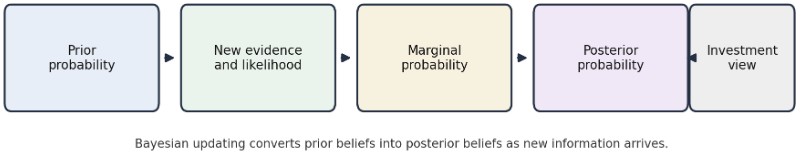
Figure 1 summarizes the logic of Bayesian updating. The analyst begins with a prior probability, observes new evidence, evaluates how likely that evidence is under different possible states, calculates the overall probability of the evidence, and then arrives at a posterior probability. The updated probability can then be used in valuation, portfolio allocation, credit analysis, or risk management. The figure is intentionally shown as a process because Bayesian updating is not a one-time mechanical calculation; it is a disciplined way to revise beliefs as information arrives.
In many investment problems, \(P(B)\) is not given directly. It must be calculated using the total probability rule. If the possible states \(A_{1},A_{2},\ldots,A_{n}\) are mutually exclusive and exhaustive, the marginal probability of evidence \(B\) is:
$$P(B) = \sum_{i = 1}^{n}P\left( B \mid A_{i} \right)P\left( A_{i} \right)$$
Where:
This denominator is often the most important part of the problem. It reminds the analyst that the same evidence may occur for more than one reason. A company may raise capital because it sees attractive growth opportunities, but it may also raise capital because its balance sheet is under pressure. A rating agency may issue a negative outlook before an actual downgrade, but not every negative outlook results in a downgrade. Bayesian updating forces the analyst to evaluate all possible paths that could have produced the observed evidence.
To formulate an investment problem using Bayesian updating, the analyst should proceed in a structured way:
$$ \textbf{Table 2: Formulating a Bayesian Investment Problem} \\
\begin{array}{l|c|c}
\textbf{Step} & \textbf{Analyst’s Question} & \textbf{Example} \\
\hline
\text{Define the event} &
{\text{What probability am I trying to} \\ \text{update?}} &
{\text{Probability that EPS will exceed} \\ \text{consensus}} \\
\hline
\text{Identify the evidence} &
{\text{What new information has} \\ \text{arrived?}} &
{\text{Management announces a} \\ \text{major customer contract}} \\
\hline
\text{Set priors} &
{\text{What were the probabilities} \\ \text{before the evidence?}} &
{\text{Initial probabilities for beat,} \\ \text{meet, and miss}} \\
\hline
\text{Estimate likelihoods} &
{\text{How likely is this evidence} \\ \text{under each state?}} &
{\text{Probability of a contract} \\ \text{announcement under each EPS} \\ \text{outcome}} \\
\hline
\text{Calculate the denominator} &
{\text{How likely is the evidence} \\ \text{overall?}} &
{\text{Weighted probability of the} \\ \text{contract announcement}} \\
\hline
\text{Update} &
{\text{What is the new probability after} \\ \text{the evidence?}} &
{\text{Posterior probability of EPS} \\ \text{beating consensus}} \\
\hline
\text{Evaluate} &
{\text{What does the update imply for} \\ \text{the investment decision?}} &
{\text{Revisit valuation, position size,} \\ \text{or risk exposure}} \\
\end{array}
$$
Table 2 emphasizes that Bayesian updating is as much about problem design as it is about calculation. Poorly chosen priors or unrealistic likelihoods will produce a precise-looking answer that may not be useful. The quality of the posterior probability depends on the quality of the prior probability and the quality of the likelihood estimates.
Example 1: Updating an Earnings Forecast After New Evidence
An analyst follows Orion Data Systems, a listed enterprise software company. Before a quarterly earnings release, the analyst assigns the following prior probabilities to three mutually exclusive and collectively exhaustive earnings outcomes:
$$
\begin{array}{l|c}
\textbf{Earnings Outcome} & \textbf{Prior Probability} \\ \hline
\text{EPS exceeds consensus} & \text{0.35} \\ \hline
\text{EPS meets consensus} & \text{0.40} \\ \hline
\text{EPS falls short of consensus} & \text{0.25} \\
\end{array}
$$
Two weeks before the earnings release, Orion announces a large new cloud infrastructure contract with a global client. Based on comparable companies and prior contract announcements, the analyst estimates the following likelihoods:
Suppose we wanted to calculate the probability that Orion’s EPS will exceed consensus after observing the contract announcement. This is a posterior probability problem. The correct approach is to treat the earnings outcome as the event of interest, treat the contract announcement as the new evidence, calculate the overall probability of that evidence across all possible earnings outcomes, and then apply Bayes’ theorem.
For this example, define the events as follows:
\(A\) = the event that Orion’s EPS exceeds consensus
\(B\) = the event that Orion announces the large cloud infrastructure contract
\(P(A)\) = the prior probability that EPS exceeds consensus, equal to 0.35
\(P(B|A)\) = the likelihood of the contract announcement if EPS exceeds consensus, equal to 0.70
\(P(B)\) = the overall probability of observing the contract announcement across all three earnings outcomes
\(P(A|B)\) = the posterior probability that EPS exceeds consensus after the contract announcement; this is the quantity we want to calculate
$$
\begin{array}{l|c}
\textbf{Earnings Outcome} & {\textbf{Probability of Observing the Contract} \\ \textbf{Announcement Given the Outcome}} \\ \hline
\text{EPS exceeds consensus} & \text{0.70} \\ \hline
\text{EPS meets consensus} & \text{0.30} \\ \hline
\text{EPS falls short of consensus} & \text{0.10} \\
\end{array}
$$
Recall the formula:
$$P(A \mid B) = \frac{P(B \mid A)P(A)}{P(B)}$$
Also, use the total probability rule to calculate the denominator:
Here, the three possible states are: EPS exceeds consensus, EPS meets consensus, and EPS falls short of consensus. Because these states are mutually exclusive and collectively exhaustive, their probability-weighted likelihoods can be added to obtain the marginal probability of the contract announcement.
$$P(B) = \sum_{i = 1}^{n}P\left( B \mid A_{i} \right)P\left( A_{i} \right)$$
First, calculate the overall probability of observing the contract announcement:
$$P(B) = (0.70 \times 0.35) + (0.30 \times 0.40) + (0.10 \times 0.25) = 0.39$$
Next, update the probability that EPS exceeds consensus:
$$P\left( \text{Exceeds} \mid B \right) = \frac{0.70 \times 0.35}{0.39} = 0.6282$$
The posterior probability that EPS exceeds consensus is 62.82%, compared with the prior probability of 35.00%.
The other two posterior probabilities are:
$$P\left( \text{Meets} \mid B \right) = \frac{0.30 \times 0.40}{0.39} = 0.3077$$
$$P\left( \text{Falls short} \mid B \right) = \frac{0.10 \times 0.25}{0.39} = 0.0641$$
The three posterior probabilities sum to 1, allowing for rounding:
$$0.6282 + 0.3077 + 0.0641 = 1.0000$$
The announcement does not prove that the company will beat consensus. It simply changes the analyst’s probability assessment. In this case, the evidence is much more likely if EPS exceeds consensus than if it falls short, so the posterior probability of an earnings beat rises materially.
Example 2: Evaluating an Investment Screen
A quantitative analyst uses a fundamental screen to identify companies likely to deliver above-sector cash-flow growth over the next year. The analyst estimates that 32% of companies in the investable universe have durable cash-flow growth prospects. The screen is not perfect, but it is informative:
Suppose we wanted to calculate the probability that a company has durable cash-flow growth prospects after it passes the fundamental screen. The screen result is the new evidence, while durable growth is the event whose probability is being updated. The approach is to calculate the overall probability that a company passes the screen and then use Bayes’ theorem to convert the prior probability of durable growth into a posterior probability.
For this example, define the events as follows:
\(A\) = the event that a company has durable cash-flow growth prospects
\(A^c\) = the complementary event that a company does not have durable cash-flow growth prospects
\(B\) = the event that a company passes the fundamental screen
\(P(A)\) = the prior probability of durable growth, equal to 0.32
\(P(A^c)\) = the prior probability of no durable growth, equal to 0.68
\(P(B|A)\) = the probability of passing the screen given durable growth, equal to 0.78
\(P(B|A^c)\) = the probability of passing the screen given no durable growth, equal to 0.27
\(P(A|B)\) = the probability that a company has durable growth after it passes the screen; this is the quantity we want to calculate
Start by quoting the formula:
$$P(A \mid B) = \frac{P(B \mid A)P(A)}{P(B)}$$
Also, calculate the marginal probability of passing the screen:
$$P(B) = P(B \mid A)P(A) + P\left( B \mid A^{c} \right)P\left( A^{c} \right)$$
The probability of passing the screen is:
$$P\left( \text{Passes screen} \right) = (0.78 \times 0.32) + (0.27 \times 0.68) = 0.4332$$
The updated probability of durable growth, given that a company passes the screen, is:
$$P\left( \text{Durable growth} \mid \text{Passes screen} \right) = \frac{0.78 \times 0.32}{0.4332} = 0.5762$$
A company that passes the screen has an updated probability of durable growth of 57.62%, compared with the prior probability of 32.00%. The screen is useful because it improves the probability assessment, but it does not eliminate uncertainty. More than 40% of companies that pass may still fail to deliver durable growth, based on the analyst’s assumptions.
Bayesian updating requires judgment. A posterior probability may look precise, but it depends on the inputs. If the prior probability is stale, or if the likelihood estimates are based on a non-representative sample, the final result may be misleading. This is especially important in markets where data-generating processes change. A signal that worked well during a low-rate environment may be less reliable after a shift in inflation, monetary policy, liquidity, or sector leadership.
In addition, evidence must be interpreted relative to competing explanations. Suppose a company issues equity. That could be a positive signal if the funds will finance a high-return project. It could be a negative signal if the company is repairing a stressed balance sheet. The Bayesian approach forces the analyst to weigh both possibilities rather than reacting mechanically to the announcement.
Finally, Bayesian updating is naturally iterative. Today’s posterior probability can become tomorrow’s prior probability. As earnings results, guidance, credit spreads, macroeconomic releases, and management actions arrive, the analyst can continue revising the probability distribution in a disciplined way.
Question
A credit analyst estimates that the prior probability of a corporate issuer being downgraded within the next six months is 18%. Therefore, the probability of no downgrade is 82%. A rating agency then assigns the issuer a negative outlook. Based on the analyst’s historical review, a negative outlook occurs 72% of the time before a downgrade and 16% of the time when no downgrade occurs.
The posterior probability of a downgrade, given the negative outlook, is closest to:
- 18.0%
- 49.7%
- 72.0%
The correct answer is B.
The problem asks for the posterior probability of a downgrade after the negative outlook has been observed. Therefore, let the downgrade be the event of interest, and the negative outlook be the evidence. We first calculate the overall probability of receiving a negative outlook and then apply Bayes’ theorem.
Recall the formula:
$$P(D \mid O) = \frac{P(O \mid D)P(D)}{P(O)}$$
Where:
- \(D\) is the event that the issuer is downgraded within six months
- \(O\) is the event that the issuer receives a negative outlook
- \(P(D \mid O)\) is the posterior probability of a downgrade given the negative outlook
- \(P(O \mid D)\) is the probability of a negative outlook given that a downgrade occurs
- \(P(D)\) is the prior probability of a downgrade
- \(P(O)\) is the marginal probability of a negative outlook
The marginal probability of a negative outlook is:
$$P(O) = P(O \mid D)P(D) + P\left( O \mid D^{c} \right)P\left( D^{c} \right)$$
Where:
- \(D^{c}\) is the complement of \(D\), meaning no downgrade occurs.
- \(P\left( O \mid D^{c} \right)\) is the probability of a negative outlook given no downgrade.
- \(P\left( D^{c} \right)\) is the prior probability of no downgrade.
First, calculate the marginal probability of a negative outlook:
$$P(O) = (0.72 \times 0.18) + (0.16 \times 0.82) = 0.2608$$
Then apply Bayes’ theorem:
$$P(D \mid O) = \frac{0.72 \times 0.18}{0.2608} = 0.4969$$
The posterior probability of a downgrade is approximately 49.7%. The negative outlook is informative because it raises the probability of a downgrade from the 18.0% prior to a 49.7% posterior. It does not, however, imply a 72.0% probability of downgrade; 72.0% is the likelihood of the outlook given a downgrade, not the probability of a downgrade given the outlook.
A is incorrect because it is the prior probability of downgrade before incorporating the negative outlook.
C is incorrect because it uses \(P(O \mid D)\), the probability of a negative outlook given downgrade, as though it were \(P(D \mid O)\), the probability of downgrade given a negative outlook.
Strengthen your understanding of the central limit theorem, sampling distributions, and its applications in finance for CFA Level I with study notes, practice questions, and mock exams.


Get Ahead on Your Study Prep This Cyber Monday! Save 35% on all CFA® and FRM® Unlimited Packages. Use code CYBERMONDAY at checkout. Offer ends Dec 1st.